
Most people know “compound interest” is powerful. Few can say what it actually does to their numbers. This article is the plain-English version — with every figure pulled from a real calculation you can reproduce in a minute.
The setup we’ll use throughout: you invest $10,000 once, then add $500 every month, and earn a steady 7% a year for 20 years. That’s it.
The 7% rate in this example is a modeling assumption, not a forecast. Investor.gov explains that investments do not have a set rate of return and notes that some experts use 7–10% as a useful long-term estimate for diversified U.S. stock investments based on historical averages. Long-run market history is also available from NYU Stern. Caspenda keeps 7% editable so you can test lower and higher scenarios.
The one number that explains everything
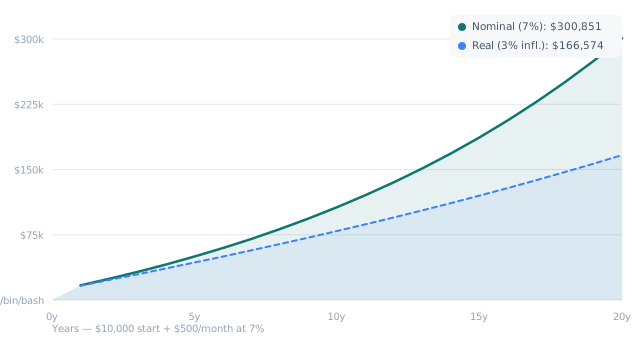
After 20 years, that plan is worth about $300,851.
Stop on that number for a second, because here’s what most people miss. You only put in $130,000 of your own money — the $10,000 start plus 240 months of $500. The other $170,851 is modeled investment growth. Under this constant-return scenario, nearly 57% of the final balance comes from growth rather than contributions.
If someone had told you “you can turn $130,000 into $300,000 just by being consistent,” you’d probably nod and move on. The numbers hit differently when you see your money and the growth split out.
Why the curve bends
Compounding isn’t a straight line. It’s a curve that gets steeper the longer you run it, because your returns start earning returns of their own.
Year 1: your $10,000 earns about $700, and you add $6,000. Year 20: the balance grows by more than $20,000 in a single year — more than triple your annual contributions.
The first decade feels painfully slow. That’s not a bug. The last few years are where the real work happens, and that’s exactly why starting earlier beats starting “smarter” later.
Time beats timing — in numbers
Here’s the same $10,000 + $500/month plan at 7%, but with different horizons:
| Years | Total invested | Final balance | Growth |
|---|---|---|---|
| 5 | $40,000 | $49,493 | $9,493 |
| 10 | $70,000 | $100,337 | $30,337 |
| 15 | $100,000 | $177,317 | $77,317 |
| 20 | $130,000 | $300,851 | $170,851 |
Notice the pattern: each extra five years roughly doubles the growth. The first five years produce under $10,000 of growth; the last five years alone add more than $90,000. You can run these exact numbers on our compound interest calculator in seconds.
The rule of 72, in your head
Want a fast sanity check without a calculator? The Rule of 72 says: divide 72 by your annual return to get the years to double.
Years to double ≈ 72 ÷ annual return (%)

At 7%:  72 ÷ 7 ≈ 10.3 years
At 10%: 72 ÷ 10 ≈ 7.2 years
The exact formula — solving (1 + r)ⁿ = 2 for n — gives a slightly different answer than the shortcut:
n = ln(2) / ln(1 + r)
For returns between 4% and 15%, the rule and the exact math agree within a few percent. That’s good enough for a back-of-the-napkin check.
The honest caveats
Three things make real-world results smaller than the headline number:
- Volatility. Markets don’t return 7% every year. They swing, and the order of those swings matters for your final number.
- Taxes and fees. A 7% gross return can easily become 5.5% after fees and taxes. That single change cuts the 20-year result from ~$301k to ~$230k.
- Inflation. $300,851 in 2046 will not buy what $300,851 buys today. At 3% annual inflation, that nominal balance is worth roughly $166,574 in today’s dollars. A 3% long-run inflation assumption sits close to recent U.S. reality — the Consumer Price Index ran about 3.4% year-over-year as of mid-2026, per the U.S. Bureau of Labor Statistics (Source: BLS CPI).
That’s why we added the inflation toggle to the calculator — check “Adjust for inflation” and you’ll see the real, today-dollar version of your result alongside the nominal one.
What this means for you
- Start now, even small. $200 a month for 30 years beats $800 a month for 10 years in most scenarios. The curve rewards time more than size.
- Automate it. The single most reliable lever is a contribution you never have to decide about.
- Check your real return. Use a conservative rate — 5–6% after fees — and the inflation-adjusted number. The honest picture is the useful one.
Compound interest is not a get-rich trick. It’s arithmetic that rewards patience and punishes delay — and it works for anyone who starts.
Educational content, not financial advice. See our methodology and disclaimer.